Written and reviewed per our independent editorial methodology. Advertiser disclosure: BanksMobile may earn compensation from some partner links on this page. This never influences our ratings, which follow our rating methodology. Read our disclaimer.
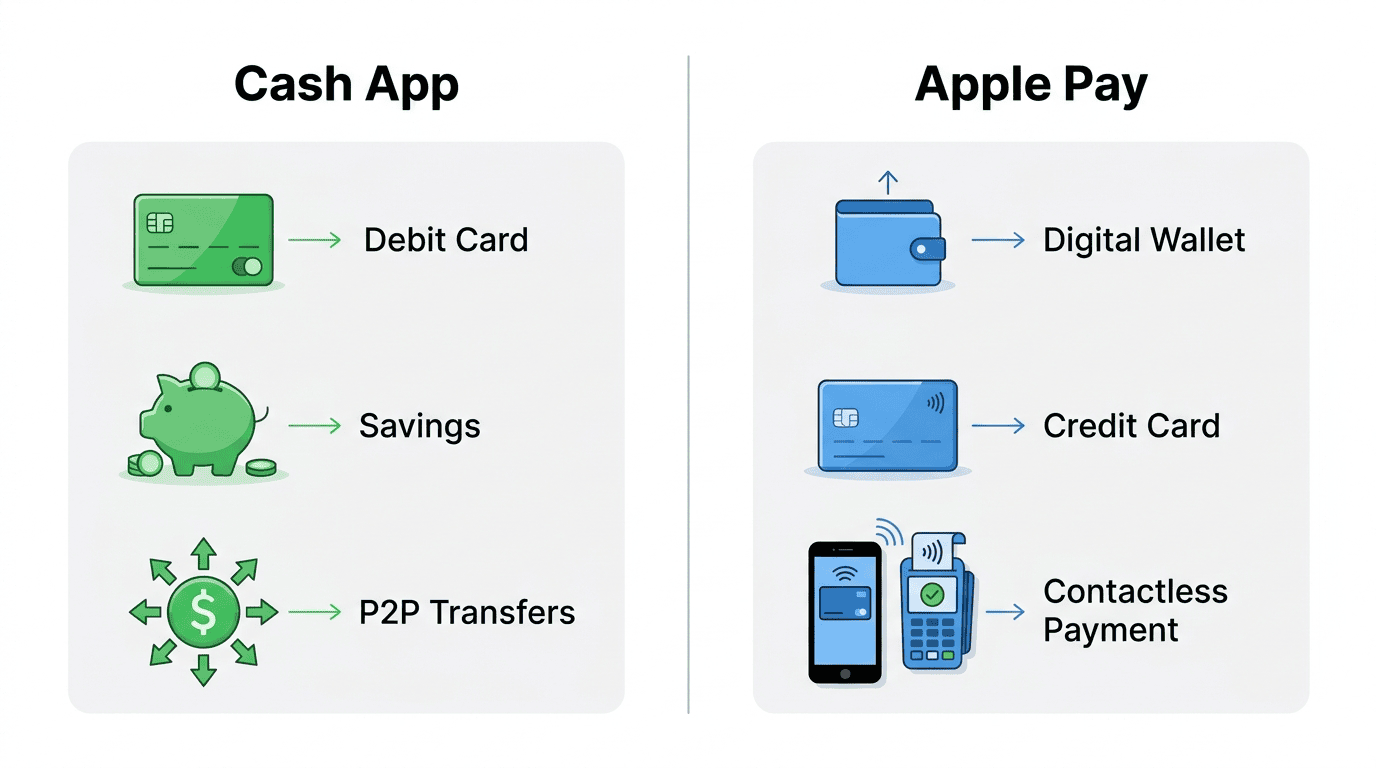
Cash App and Apple Pay serve different purposes. Cash App is a standalone financial app with its own balance for peer-to-peer payments and a savings account offering up to 3.5% APY. Apple Pay is a digital wallet that stores your existing cards for contactless payments, while Apple Cash is used for sending money to other Apple users.
Let’s clear this up right away: comparing Cash App vs Apple Pay is like comparing a multi-tool to a specific wrench. Cash App is a full-featured payment app with its own balance, a debit card, savings, and even investing options.
Apple Pay, on the other hand, is primarily a digital wallet that lets you use your existing bank cards for contactless payments, with Apple Cash acting as its peer-to-peer payment feature.
Think of it this way: you load money onto your Cash App balance to use its features, much like a prepaid account. With Apple Pay, you’re simply using a digital version of the plastic cards already in your wallet. Your choice depends entirely on what you need to do.
In this guide, I’ll break down the real-world differences in how you send money, pay in stores, save, and handle fees. We’ll look at the fine print so you can confidently decide which app, or combination of apps, works best for your financial life.
- ✓Cash App is a versatile financial app available on both Android and iPhone, offering a stored balance, debit card, savings, and borrowing.
- ✓Apple Pay is an iOS-exclusive digital wallet for contactless payments using your existing cards; Apple Cash is its separate P2P feature.
- ✓For savings, Cash App Savings currently offers a tiered APY up to 3.5%, while Apple Card Savings is a more traditional account linked to the Apple Card.
- ✓Cash App offers a small-dollar loan feature called Borrow, which Apple Pay does not have an equivalent for.
- ✓Both services use partner banks to provide FDIC pass-through insurance on eligible balances, but they are not banks themselves.
Table of Contents
What’s the Core Difference Between Cash App and Apple Pay?
The most important thing to understand is their fundamental design. Cash App is a self-contained financial ecosystem. You add money to your Cash App balance and then use that balance to pay friends, shop with the Cash App Card, or move it into savings.
It functions like a simplified bank account, giving you a central hub for specific financial activities. You can even receive your paycheck directly into your Cash App account.
Apple Pay, by contrast, is a convenience layer. It doesn’t hold your money for store purchases. Instead, it securely stores digital versions of your existing credit and debit cards.
When you tap your iPhone to pay at a store, Apple Pay facilitates the transaction using your selected card. The money comes directly from your linked bank account or credit line, not from an ‘Apple Pay balance’.
The exception is Apple Cash. This is a separate digital card inside your Wallet app that does hold a balance, used specifically for sending and receiving money from other Apple users. You can fund it with a debit card or have money you receive collect there.
Sending Money to Friends: Which Is Easier?
For pure peer-to-peer (P2P) payments, both apps get the job done, but their reach is different. Cash App is platform-agnostic, meaning you can send money to anyone with the app, whether they use an iPhone or an Android device.
This makes it a more universal tool for splitting a dinner bill with a diverse group of friends.
You send money directly from your Cash App balance or a linked card to another person’s $Cashtag. They receive it in their Cash App account instantly. They can then spend it from their balance, use their Cash App Card, or transfer it out to their bank.
Apple Cash works seamlessly between Apple devices. You can send money right from the Messages app, making it feel very integrated if you and your friends are all in the Apple ecosystem. The funds land in the recipient’s Apple Cash card in their Wallet app.
The major limitation is its exclusivity. You cannot send Apple Cash to an Android user. This makes it less flexible than Cash App for P2P payments if your social circle uses different types of phones.
Transfers out to your bank account are free with both services if you can wait a few business days. For instant transfers, both typically charge a fee. Cash App’s fee is variable and shown in the app before you confirm, while Apple Cash also has its own fee structure for instant transfers.
Who Wins for In-Store and Online Shopping?
When it comes to paying at a register, Apple Pay is the clear winner in terms of widespread acceptance and ease of use. It uses NFC (Near Field Communication) technology, which is the standard for tap-to-pay at millions of retail locations worldwide.
You simply hold your iPhone or Apple Watch near the terminal, authenticate with Face ID or Touch ID, and the payment is processed using your default card. Apple itself doesn’t charge you a fee for this; you’re just using your card as you normally would.
Cash App offers two ways to pay in stores. The primary method is the Cash App Card, a physical Visa debit card linked to your Cash App balance. You can use it anywhere Visa is accepted, just like a traditional bank debit card.
The second method is Cash App Pay, which lets you scan a QR code at participating merchants. While growing, this is far less common than the tap-to-pay terminals that work with Apple Pay.
For online shopping, the story is similar. Apple Pay is a common checkout option on websites and in apps, offering a fast and secure way to pay without typing in your card details. Cash App Pay is an option at some online stores, but Apple Pay has a much larger footprint.
How Do Their Savings Options Compare?
Here’s where the two services take very different approaches to helping you save. Cash App offers a feature called Cash App Savings. It’s not a full-fledged bank account, but a simple place to set aside money from your main Cash App balance.
As of May 1, 2026, Cash App Savings offers a 1.5% Annual Percentage Yield (APY) for all users with a Cash App Card. If you upgrade to the Cash App Green account, that rate jumps to 3.5% APY. Interest accrues daily and is paid out monthly.
You can start saving with just $1, and there are no monthly fees or minimum balance requirements. It’s a very accessible, high-yield option for money you’re already keeping within the Cash App ecosystem. The rates are variable and can change.
Apple’s offering, the Savings account from Goldman Sachs, is exclusively for Apple Card owners. The money you earn from Daily Cash back on your Apple Card purchases is automatically deposited into this high-yield savings account.
You can also deposit additional funds into it from a linked bank account. While Apple’s official site from September 23, 2026 confirms the account is provided by Goldman Sachs Bank USA, it does not state the current numerical APY.
This is a more formal savings account, whereas Cash App Savings is a feature of the payment app.
Can You Borrow Money with Cash App or Apple Pay?
If you need access to a small, short-term loan, Cash App has a feature that Apple Pay does not. It’s called Cash App Borrow. Eligible users can borrow amounts ranging from $20 up to a personal limit that could reach $500.
Here’s the deal: This isn’t available to everyone. Eligibility is based on factors like your state of residence, your Cash App usage, and your credit history. The feature is currently unavailable in Colorado, Iowa, and Oregon.
Cash App states that first-time borrowers can often qualify for up to $400. The loan comes with a flat fee, and you typically have four weeks to pay it back. It’s designed as a small-dollar loan to cover minor shortfalls, not a major line of credit.
It’s important to note that Apple Pay and Apple Cash have no comparable borrowing feature. While Apple does offer the Apple Card, a credit card issued by Goldman Sachs, this is a separate product that requires a credit application and is not integrated into Apple Pay as a loan service.
Cash App Borrow is only available to eligible users. According to Cash App, the average first-time borrower limit for active spenders was $153 as of October 1, 2025. Always borrow responsibly and understand the fees and repayment terms before accepting a loan.
Is your money safe? A look at FDIC insurance
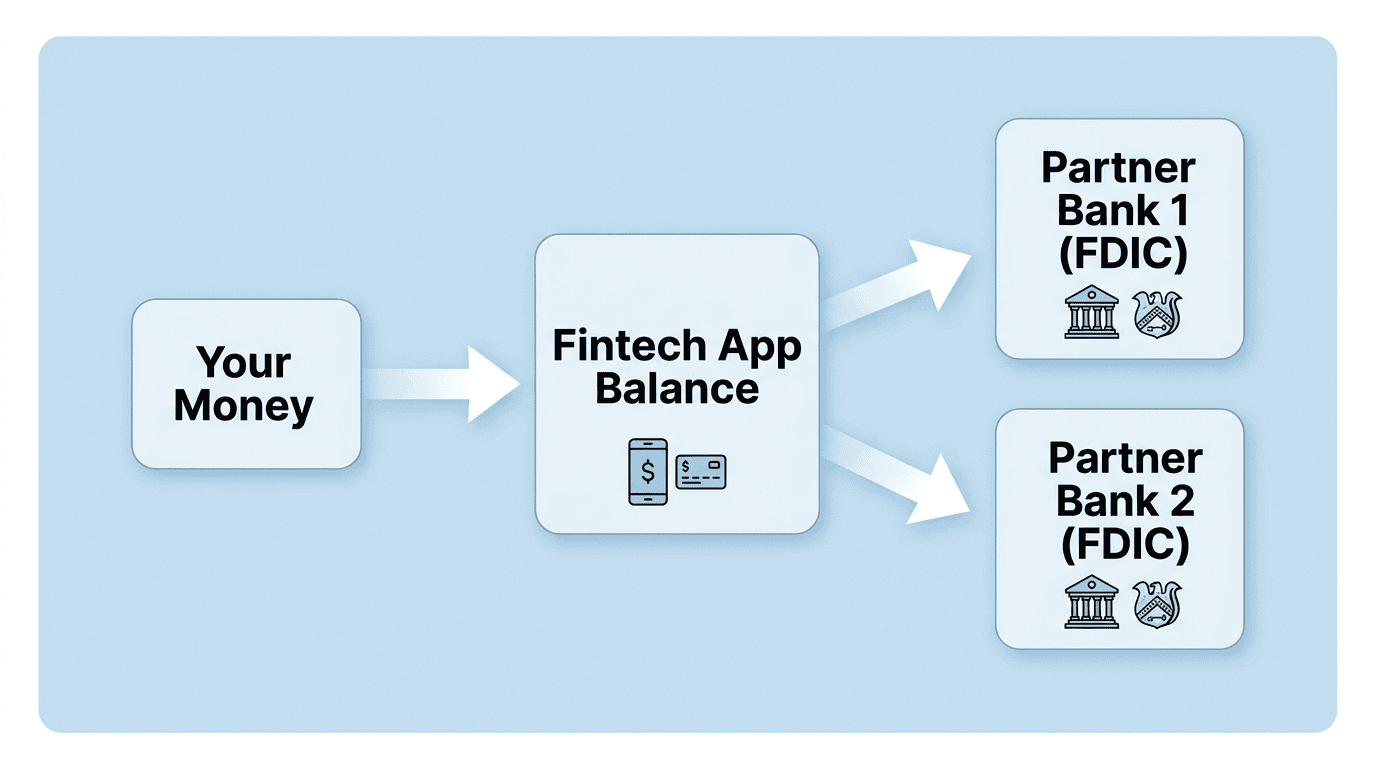
A common question is whether your money is safe in these apps. Neither Cash App nor Apple is a bank. However, they partner with FDIC-member banks to offer pass-through deposit insurance on eligible balances, up to the standard $250,000 limit.
For Cash App, your balance can be covered by FDIC insurance if you have a Cash App Card or have set up direct deposit. Cash App works with partner banks like Wells Fargo Bank, N.A. and Sutton Bank to hold customer funds and provide this protection.
Your Cash App Savings balance is held for your benefit at Wells Fargo Bank, N.A., Member FDIC, making it eligible for that same pass-through insurance coverage.
Similarly, your Apple Cash balance is held at Green Dot Bank, Member FDIC. This means the money on your Apple Cash card is also eligible for FDIC insurance, subject to applicable limits.
If you have an Apple Card Savings account, those funds are held at Goldman Sachs Bank USA, Salt Lake City Branch, Member FDIC. This structure provides the security you’d expect from a traditional bank savings account.
You can learn more about how this works on the FDIC’s official website.
- Cash App Balance: Pass-through FDIC insurance via partners like Wells Fargo Bank, N.A. and Sutton Bank.
- Cash App Savings: Held at Wells Fargo Bank, N.A., Member FDIC.
- Apple Cash Balance: Held at Green Dot Bank, Member FDIC.
- Apple Card Savings: Held at Goldman Sachs Bank USA, Member FDIC.
The Final Verdict: Which App Should You Use?
So, after comparing Cash App vs Apple Pay, the right choice really boils down to your phone and your financial habits. There isn’t a single ‘best’ app, only the best app for a specific job.
Choose Cash App if: You want an all-in-one financial app that works on any smartphone. It’s ideal if you need to send money to both iPhone and Android users, want an easy-access high-yield savings option, or might need the small borrowing feature.
Choose Apple Pay if: You’re an iPhone user who wants the most seamless way to pay in stores and online. It’s the top choice for convenience and security at checkout, leveraging the cards you already have. Use its companion, Apple Cash, for quick payments to other Apple users.
Many people, myself included, use both. I use Apple Pay for almost all of my in-store purchases because it’s fast and secure. I use Cash App to split bills with friends who have Androids or to take advantage of its unique features like Savings and Boosts.
There’s no reason to pick just one. Think of Apple Pay as your digital wallet and Cash App as your flexible digital pocket money and P2P tool. Using them together gives you the best of both worlds.
Frequently Asked Questions
What is the main drawback of Cash App vs Apple Pay?
The main drawback of Cash App is that using its debit card requires you to pre-load a balance. For Apple Pay, the main drawback is its exclusivity; it only works on Apple devices, and you cannot use Apple Cash to pay Android users.
Can I send money from Cash App to Apple Pay?
You cannot send money directly from Cash App to an Apple Pay wallet. You would need to transfer the money from your Cash App account to your linked bank account first. Then, you can use the debit card associated with that bank account to fund Apple Cash or make a payment.
Which is safer, Cash App or Apple Pay?
Both are very secure. Apple Pay is arguably safer for in-store transactions because it uses tokenization, meaning your actual card number is never shared with the merchant. Cash App is also secure, using encryption and fraud detection, and offers FDIC pass-through insurance on eligible balances, just like Apple Cash.
Is the Cash App vs Apple Pay savings rate better?
Cash App Savings currently advertises a higher maximum rate (up to 3.5% APY with Cash App Green) than many traditional savings accounts. The rate for the Apple Card Savings account is variable and not publicly listed in the same way, so a direct comparison is difficult without checking the app.
Do I need a bank account for Cash App or Apple Pay?
For Apple Pay, you absolutely need a debit or credit card from a supported bank. For Cash App, you can receive money without a bank account, but you’ll need one to transfer your Cash App funds out. You can also fund Cash App at participating retailers.