Written and reviewed per our independent editorial methodology.
In the Chime vs SoFi vs Ally direct deposit comparison, SoFi is the best for users seeking a high APY and a substantial cash bonus with their direct deposit. Chime and Ally are stronger contenders for simple, no-fee banking with robust overdraft protection and early payroll access.
Choosing where to send your paycheck is a bigger decision than ever. In the battle of Chime vs SoFi vs Ally, direct deposit features have become a key differentiator. These digital banking leaders are no longer just about avoiding monthly fees; they’re competing on who can get you your money faster, pay you more interest, and even offer you cash bonuses just for signing up.
This isn’t a simple choice. Each bank has a unique value proposition. SoFi tempts users with high-yield interest rates and some of the most generous direct deposit bonuses on the market.
Chime focuses on user-friendly features like its SpotMe overdraft protection and getting you paid up to two days early. Ally Bank, a pioneer in online banking, blends a solid APY with fee-free overdraft coverage and a massive ATM network.
We’re going to break it all down. This analysis cuts through the marketing noise to give you a factual Chime vs SoFi vs Ally direct deposit comparison for 2026. We’ll examine the fine print on early pay, interest rates, cash bonuses, overdraft rules, and FDIC insurance so you can confidently decide which account deserves your direct deposit.
- ✓SoFi offers the highest potential APY and the only significant cash bonus for setting up direct deposit in 2026.
- ✓Chime provides the earliest potential access to your paycheck (up to 2 days) and a simple, fee-free overdraft feature called SpotMe.
- ✓Ally Bank offers a competitive savings APY, a large fee-free ATM network, and up to $10 per month in out-of-network ATM fee reimbursements.
- ✓All three banks have eliminated monthly maintenance fees, making every option in the Chime vs SoFi vs Ally direct deposit comparison a strong alternative to traditional banking.
Table of Contents
Chime vs SoFi vs Ally Direct Deposit: How Do They Stack Up at a Glance?
When you’re comparing Chime vs SoFi vs Ally direct deposit options, you’re looking at three of the strongest players in digital finance. Each has carved out a specific niche. Understanding their core strengths is the first step in making the right choice for your money.
SoFi positions itself as an all-in-one financial hub. It combines high-yield checking and savings with investing, loans, and more. Its direct deposit benefits are designed to pull you deeper into its ecosystem with top-tier interest rates and bonuses.
Chime, on the other hand, prioritizes simplicity and financial wellness for the everyday user. Its main draws are straightforward features like early payday and a forgiving overdraft system. It’s built for people who want a no-fuss banking experience.
Ally Bank bridges the gap between a fintech and a full-service online bank. It has a long-standing reputation for customer service and competitive rates. It attracts users who want the reliability of an established bank with the perks of a modern digital platform.
The best Chime vs SoFi vs Ally direct deposit choice depends entirely on your financial goals. Do you want to maximize returns, avoid overdraft fees, or have a simple and reliable place to park your paycheck? Let’s dig into the specifics.
Chime vs SoFi vs Ally Direct Deposit Speed: Which Bank Gets You Paid the Fastest?
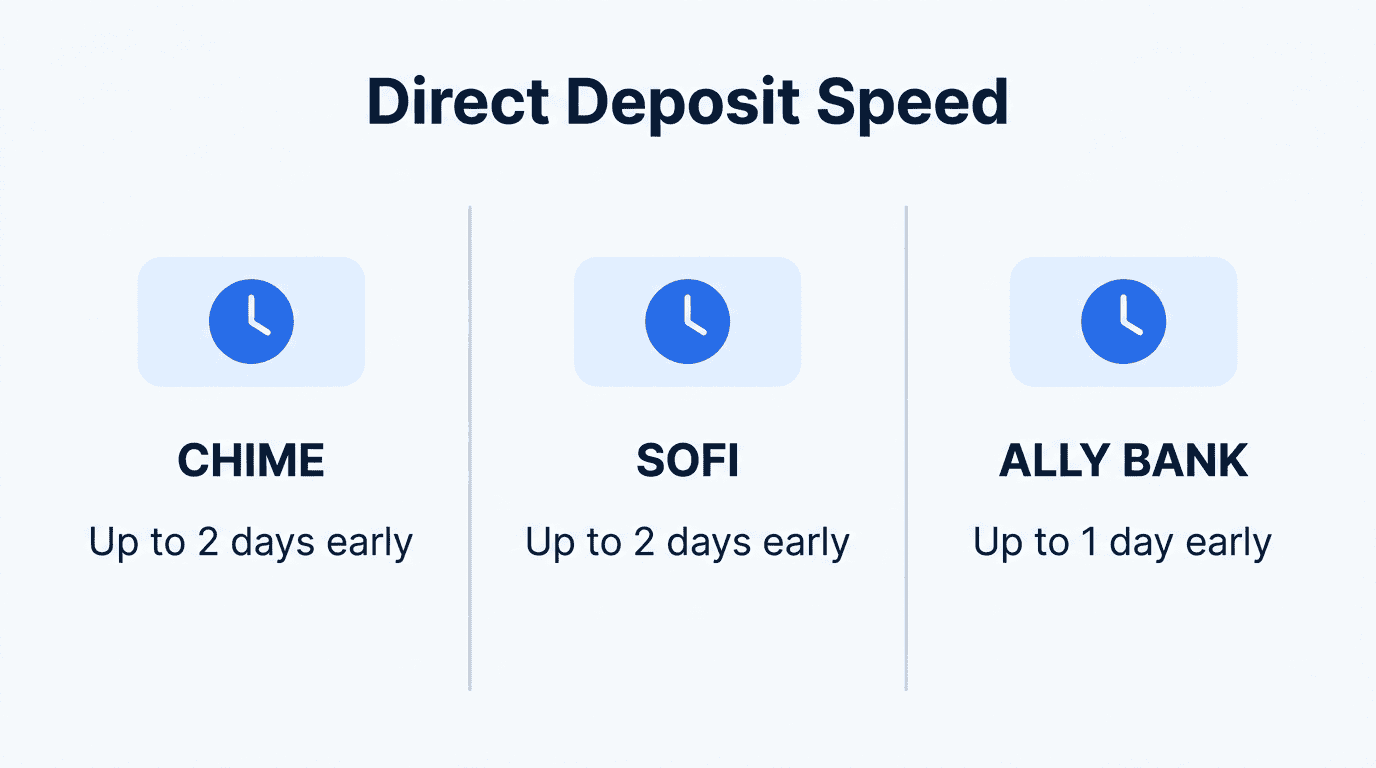
The promise of getting your paycheck early is a major selling point in any Chime vs SoFi vs Ally direct deposit comparison. Both Chime and SoFi lead the pack here, offering access to your direct deposit funds up to two days before your official payday.
This can be a significant advantage for managing cash flow and avoiding late fees on bills.
Here’s the deal: This feature depends entirely on your employer’s payroll provider. The bank makes the funds available as soon as they receive the payment file from your payer.
If your employer is slow to submit payroll, you won’t see the money two days early, regardless of which bank you use.
Chime heavily markets its ‘up to 2 days early’ feature. For many users, this works exactly as advertised and is a primary reason they choose the service. It’s a core part of their value proposition.
SoFi offers the same two-day early access for qualifying direct deposits. It’s a standard feature of their Checking and Savings account and works seamlessly for most members.
Ally Bank is slightly more conservative, advertising direct deposit access up to one day early. While still faster than most traditional banks, it puts them a step behind Chime and SoFi in the race to get you your cash.
Ultimately, for the absolute fastest Chime vs SoFi vs Ally direct deposit access, Chime and SoFi are your best bets, with the caveat that it’s always subject to your payer’s processing schedule.
Does SoFi really pay you to set up direct deposit?
Yes, and it’s one of SoFi’s most compelling advantages in 2026. SoFi offers a tiered cash bonus for new and existing members who set up a qualifying direct deposit for the first time. This is a direct payment into your account, not a gimmick.
The promotion, running from May 15, 2026, to December 31, 2026, has two tiers. You can earn a $50 bonus by receiving at least $1,000 in eligible direct deposits within a 25-day evaluation period. This period starts from the day your first deposit lands.
For those with higher incomes, the offer gets much better. If you receive $5,000 or more in eligible direct deposits within that same 25-day window, SoFi will give you a $400 cash bonus. This is one of the most substantial direct deposit promotions available from any bank.
Let’s look at a quick example. Say your first direct deposit of $2,600 arrives on July 1st. If another $2,600 deposit arrives on July 15th, your total within the 25-day window is $5,200. You would qualify for the $400 bonus.
Neither Chime nor Ally is currently offering a comparable public cash bonus for setting up direct deposit in 2026. This makes SoFi the clear winner of the Chime vs SoFi vs Ally direct deposit bonus race for anyone looking for an immediate cash incentive to switch banks.
Earn $50 for deposits of $1,000-$4,999 or $400 for deposits of $5,000+ within 25 days of your first deposit. Offer valid 5/15/2026 to 12/31/2026.
What are the interest rates for Chime vs SoFi vs Ally direct deposit users?
Earning interest on your cash is a huge perk of digital banking. Here, the Chime vs SoFi vs Ally direct deposit differences are stark, and having a direct deposit is often the key to unlocking the best rates. SoFi stands out with its high-yield structure.
With a qualifying direct deposit, SoFi members earn 3.10% APY on savings balances and a remarkable 0.50% APY on their checking balance. This dual-yield approach is powerful, ensuring all your money is working for you, not just what’s tucked away in savings.
Ally Bank is also a strong competitor, long known for its high-yield savings account. Current rates for 2026 hover around 3.00% to 4.00% APY. While this is a fantastic rate, it applies only to your savings balance, not your checking.
Chime offers a savings account with an APY that some sources have cited as high as 3.75%. However, this rate requires careful verification directly on Chime’s site, as it is not as prominently advertised as its other features.
Their focus is less on being a yield leader and more on transactional features.
Without a direct deposit, the value proposition changes, especially for SoFi. The high APY is contingent on that regular deposit. For Ally and Chime, the savings APY is generally available without a direct deposit requirement, though features like overdraft protection may still require it.
If maximizing yield on both your spending and saving money is your top priority, SoFi’s structure is currently unmatched in the Chime vs SoFi vs Ally direct deposit comparison, provided you meet the deposit conditions.
Chime vs SoFi vs Ally Direct Deposit Accounts: How Do Fees and ATM Access Compare?
A core promise of neobanks is the elimination of frustrating fees. All three Chime vs SoFi vs Ally direct deposit contenders excel here. None of them charge monthly maintenance fees, overdraft fees, or have minimum balance requirements. This is a massive improvement over most traditional brick-and-mortar banks.
When it comes to ATM access, the networks are vast. You’re unlikely to be far from a fee-free ATM with any of these options. They all leverage large, nationwide networks to provide convenient access to your cash without penalty.
Chime boasts access to over 60,000 fee-free ATMs through the MoneyPass and Visa Plus Alliance networks. This gives users widespread coverage in retail stores, pharmacies, and grocery stores across the country.
SoFi utilizes the Allpoint Network, which provides more than 55,000 fee-free ATMs worldwide. Like Chime, these are commonly found in convenient locations like Target, CVS, and Walgreens.
Ally Bank has a slight edge in network size with access to over 75,000 ATMs, according to some sources. More importantly, Ally offers a unique perk: it reimburses up to $10 per statement cycle for fees charged at out-of-network ATMs.
This gives you the freedom to use virtually any ATM in a pinch without worrying about the cost.

What Happens If You Overdraft a Chime vs SoFi vs Ally Direct Deposit Account?
Overdraft protection is another area where these digital banks shine, but they take different approaches. They’ve replaced punitive fees with user-friendly safety nets, but the mechanics vary.
This is a critical factor in the Chime vs SoFi vs Ally direct deposit debate, as deposits often unlock these features.
Chime’s SpotMe is a standout feature. It allows eligible members to overdraft their account on debit card purchases and cash withdrawals with no fees. Eligibility and limits, which can go up to $200, are based on your account history and direct deposit activity.
Ally Bank offers a similar service called CoverDraft. For qualifying customers with regular direct deposits, Ally provides a fee-free safety net of up to $250. If you overdraft, CoverDraft kicks in, and you have 14 days to bring your balance back to positive before access to the feature is suspended.
SoFi also offers fee-free overdraft coverage. If you have monthly direct deposits of $1,000 or more, you get coverage on debit card transactions. The coverage amount is smaller, typically starting at $50, but it provides a basic buffer to prevent declined purchases.
In the Chime vs SoFi vs Ally direct deposit overdraft comparison, Chime and Ally offer more generous limits, making them better choices for users who want a more substantial safety net. SoFi’s offering is a helpful perk but less robust than its competitors’. All three are vastly superior to traditional banks that charge $35 or more per overdraft.
Is Your Money Safe With Chime vs SoFi vs Ally Direct Deposit Accounts?
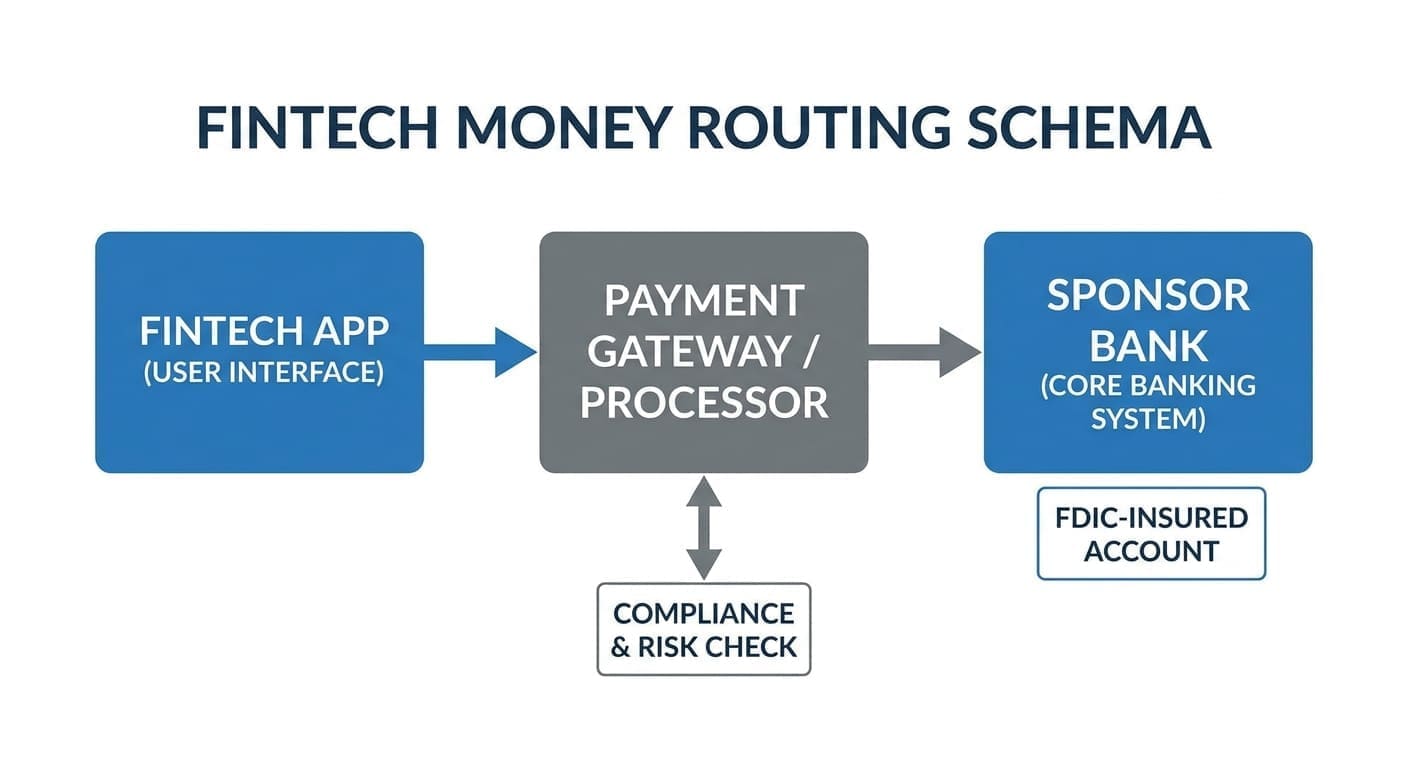
Security is paramount, and a common question is whether money in a digital bank is as safe as it is in a traditional one. The answer is a resounding yes, thanks to the Federal Deposit Insurance Corporation (FDIC). All three Chime vs SoFi vs Ally direct deposit accounts provide this crucial protection.
Chime is a financial technology company, not a bank. Its banking services are provided by The Bancorp Bank or Stride Bank, N.A., both of which are FDIC members. This means your deposits are insured up to the standard $250,000 per depositor, per insured bank, for each account ownership category.
Ally Bank is a direct FDIC-member bank. Your funds there are also insured up to the standard $250,000 limit. This is the same level of protection you would get at a major national bank like Chase or Bank of America.
You can verify any bank’s status on the official FDIC website.
SoFi takes a unique approach to maximize insurance coverage. Through a network of partner banks, SoFi is able to offer FDIC insurance on up to $3 million in deposits. They achieve this by spreading your deposits across multiple FDIC-insured institutions behind the scenes.
This enhanced coverage makes SoFi an attractive option for high-net-worth individuals who want to keep large cash balances fully insured without opening accounts at multiple banks. For most users, the standard $250,000 coverage offered by all three Chime vs SoFi vs Ally direct deposit accounts is more than sufficient.
FDIC insurance protects your money in the unlikely event of a bank failure. For both traditional and digital banks, ensuring your institution is FDIC-insured is the most important step you can take to protect your deposits.Jake Morrison, Neobank Analyst
The Verdict: Who Wins the Chime vs SoFi vs Ally Direct Deposit Battle?
After comparing the core features, a clear picture emerges. There isn’t one single ‘best’ bank, but there is a best bank for you, depending on your priorities. The right choice in the Chime vs SoFi vs Ally direct deposit matchup comes down to what you value most.
If your goal is to maximize your earnings through interest and bonuses, SoFi is the undeniable winner. The combination of a $400 cash bonus, a 3.10% APY on savings, and an industry-leading 0.50% APY on checking for direct deposit users is a financial powerhouse. The enhanced FDIC coverage is an added bonus for those with large balances.
If your main concern is avoiding fees and having a strong overdraft safety net, Chime is an excellent choice. Its SpotMe feature is simple and generous, and its two-day early payroll access is a core, reliable benefit.
It’s perfect for the user who prioritizes simplicity and cash flow management over earning high interest.
Ally Bank is the ideal middle ground in the Chime vs SoFi vs Ally direct deposit debate. It’s a fantastic option for someone who wants a high-yield savings account from an established, reputable online bank, combined with great ATM access and solid overdraft protection.
The $10 monthly reimbursement for out-of-network ATM fees is a unique and valuable perk.
Consider what you need most from a Chime vs SoFi vs Ally direct deposit account. Is it a cash bonus, a high APY, or a simple safety net? Your answer to that question will point you directly to the right account for your next paycheck.
Chime vs SoFi vs Ally Direct Deposit: Frequently Asked Questions
Do I need a minimum direct deposit amount for SoFi’s high APY?
No, any amount of qualifying direct deposit per month will unlock the 3.10% savings APY and 0.50% checking APY. However, to get the cash bonus, you need to deposit at least $1,000 within the 25-day evaluation period.
Is Chime a real bank?
Chime is a financial technology company, not a bank. Its banking services are provided by its FDIC-insured partners, The Bancorp Bank or Stride Bank, N.A. This means your money is protected just as it would be at a traditional bank.
Can I really use any ATM with Ally Bank?
You can use any Allpoint+ ATM for free. If you use an ATM outside of that network, you may be charged a fee by the ATM owner, but Ally will reimburse you for up to $10 of those fees per statement cycle.
Which Chime vs SoFi vs Ally direct deposit account is best if I frequently overdraft?
Both Chime and Ally are excellent choices. Chime’s SpotMe offers up to $200 in fee-free overdrafts, while Ally’s CoverDraft offers up to $250. Both are significantly more generous than SoFi’s standard overdraft protection.
Is the SoFi direct deposit bonus available for existing customers?
Yes, the 2026 promotion is available for eligible existing SoFi members as long as they have not previously enrolled in or had a direct deposit set up in their SoFi Checking and Savings account.
Will I always get paid two days early with Chime or SoFi?
Not guaranteed. In the Chime vs SoFi vs Ally direct deposit race, the ‘up to two days early’ feature depends on when your employer’s payroll provider sends the payment file to the bank. While it often works as advertised, delays from the payer can affect the timing.