Written and reviewed per our independent editorial methodology. Advertiser disclosure: BanksMobile may earn compensation from some partner links on this page. This never influences our ratings, which follow our rating methodology. Read our disclaimer.
Chime is superior for primary banking, offering fee-free overdrafts up to $200 with SpotMe and a vast ATM network of over 47,000 locations. Cash App excels at peer-to-peer payments and in-app investing in stocks and Bitcoin, making it a better supplemental finance tool.
The verdict on the chime vs cash app debate is clear: Chime is the superior choice for a primary bank account replacement, while Cash App is the winner for peer-to-peer payments and simple investing.
Both fintech apps offer compelling mobile-first experiences, but they serve fundamentally different purposes. Understanding this core distinction is the key to choosing the right one for your financial needs.
Chime has built a comprehensive suite of banking services designed to replace a traditional bank. It offers a checking account, a high-yield savings account, early direct deposit, and a unique fee-free overdraft feature. Its entire model is geared towards being your financial hub.
In contrast, Cash App began as a simple peer-to-peer payment service and has since expanded. While it now offers a debit card and savings features, its strengths remain in social payments, easy stock investing, and Bitcoin trading.
It functions more like a digital wallet with banking features attached, rather than a full-fledged banking service.
- ✓Chime is better for everyday banking with its robust checking account, SpotMe overdraft protection, and large fee-free ATM network.
- ✓Cash App is the undisputed leader for peer-to-peer (P2P) payments and accessible investing in stocks and Bitcoin.
- ✓Chime generally offers higher potential savings APYs through its tiered programs, but Cash App’s base rate can be competitive.
- ✓Neither are traditional banks. Both are fintech companies that partner with FDIC-insured banks to hold and protect your deposits.
Table of Contents
Chime vs Cash App: A Head-to-Head Feature Showdown
When you place Chime and Cash App side-by-side, their different philosophies become immediately apparent. Chime is structured like a modern bank, focusing on core deposit accounts and spending tools. Its features are designed for stability and daily financial management.
Cash App, on the other hand, prioritizes speed and social transactions. Its interface is built around sending money to friends, making quick purchases with the Cash Card, and dipping a toe into the investing world. It’s less about long-term savings and more about managing your fluid cash.
Think of it this way. You’d use Chime to receive your paycheck, pay your rent, and build your emergency fund. You’d use Cash App to split a dinner bill with friends, buy a coffee, or purchase a fractional share of a popular stock.
Both platforms have successfully eliminated common banking fees like monthly maintenance charges, which is a major draw for consumers tired of traditional bank costs. However, their approaches to other services like overdrafts and ATM access diverge significantly.
This comparison will break down the essential differences in accounts, rates, fees, and extra features to give you a clear picture of which app aligns with your financial goals. Let’s get into the specifics.
Account Fees and Core Banking: Who Offers More for Free?
Both Chime and Cash App have built their brands on being low-fee alternatives to traditional banking. You won’t find monthly maintenance fees or minimum balance requirements on either platform. This is a significant advantage for anyone looking to avoid being nickel-and-dimed.
Chime provides a Checking Account and a Savings Account. These function as you’d expect from a bank, with a debit card for spending and routing numbers for direct deposits and bill pay. It’s a complete package for managing your core finances.
Cash App’s setup is slightly different. It provides a single cash balance that you can spend with the Cash Card. You can also enable a Savings feature, but it’s more of a partition of your main balance than a separate, fully-featured account.
Here’s the critical distinction: Chime is a financial technology company, not a bank. Its banking services are provided by its partners, The Bancorp Bank, N.A., or Stride Bank, N.A.
This is how your deposits get FDIC insurance up to the standard $250,000 limit.
Similarly, Cash App is not a bank. It partners with FDIC-member banks to provide its banking services and insure deposits. This fintech-bank partnership model is common in the industry and is crucial for consumer protection.
Which App Offers a Better Savings APY?
For savers, the Annual Percentage Yield (APY) is a top consideration. In the chime vs cash app matchup, Chime currently offers a more complex but potentially more rewarding tiered structure for its savings rates.
Chime’s standard Savings Account offers a 0.75% APY. However, select members may qualify for higher tiers like Chime Plus at 2.75% APY or Chime Prime at 3.75% APY. These rates, verified as of July 13, 2026, require meeting specific eligibility criteria and can change.
Cash App Savings offers a base rate of 1.5% APY. According to Cash App’s own savings page (verified October 5, 2026), this is boosted to 3.5% APY for users with Cash App Green status, which may have its own requirements. You only need $0.01 in your account to start earning interest with either service.
For example, a $5,000 balance in a standard Chime account at 0.75% APY would earn about $37.50 in a year. The same balance in a standard Cash App Savings account at 1.5% APY would earn $75. The calculus changes dramatically if you qualify for the higher tiers.
The bottom line: If you don’t qualify for the premium tiers, Cash App’s standard 1.5% APY is superior to Chime’s 0.75%. However, if you are eligible for Chime Prime, its 3.75% APY significantly outperforms Cash App’s best offer.
You must check current terms before making a decision, as these rates are variable.
The APYs cited are based on data from July 2026 and are subject to change at any time. Always verify the current rates directly with Chime or Cash App before opening an account.
Chime SpotMe vs. Cash App Borrow: Overdraft Options Explained
Overdraft protection is a feature where Chime clearly pulls ahead. Chime’s SpotMe is an optional, fee-free service that lets you overdraw your account on debit card purchases without penalty. This is a game-changer compared to the hefty overdraft fees charged by traditional banks.
Eligibility for SpotMe depends on your account history and direct deposit activity. Coverage typically starts at $20 and can increase to $200 over time for active members. The negative balance is simply repaid the next time you add funds to your account.
Cash App does not offer a direct equivalent to SpotMe. Instead, eligible users may be able to access a feature called Cash App Borrow. This is not overdraft protection; it’s a short-term loan.
Borrow allows you to take out a small loan, reportedly up to $500, which you must repay within a set timeframe. Unlike SpotMe, Borrow comes with a flat fee. It’s a useful feature for emergencies but functions very differently from Chime’s seamless, fee-free overdraft coverage.
For users who want a safety net for their checking account to avoid declined purchases, Chime’s SpotMe is the far superior and more consumer-friendly option.
ATM Access and Fees: Who Has the Better Network?
Getting cash without paying fees is a major factor in choosing a banking app. Here, Chime has a decisive advantage thanks to its extensive ATM network partnerships. Chime users have fee-free access to over 47,000 ATMs through the MoneyPass and Allpoint networks.
You can find these ATMs in common locations like Target, CVS, and Walgreens, making it convenient to withdraw cash nearly anywhere. If you must use an out-of-network ATM, Chime charges a $2.50 fee, plus any fee the ATM operator might add.
Cash App’s ATM situation is more restrictive. It does not have a large, dedicated fee-free network like Chime. The standard fee for any ATM withdrawal using the Cash Card is $2.50, plus the operator’s fee.
Cash App does offer a way to get free ATM withdrawals, but it requires meeting certain conditions. Typically, you must receive a qualifying amount in direct deposits each month to have your ATM fees reimbursed. This makes free access less reliable than with Chime.
For anyone who frequently needs to withdraw physical cash, Chime’s massive and straightforward fee-free network makes it the clear winner in this category.
Peer-to-Peer Payments: Is Chime or Cash App Faster?
When it comes to sending money to friends and family, Cash App is the undisputed champion. This is its original and core function, and the entire user experience is optimized for quick, social payments. You can send, request, and split payments with anyone on Cash App instantly.
Cash App’s P2P system is built like a social network. You have a unique $Cashtag, and you can easily find contacts. Standard transfers to your linked bank account are free and take a few business days. Instant transfers have a fee, typically between 0.5% and 2.5%.
Chime also allows users to send money instantly and for free to other Chime members using its Pay Anyone feature. This works well within the Chime ecosystem. However, it’s not the universal P2P platform that Cash App has become.
Sending money from Chime to an external bank account is a standard bank transfer, which isn’t as seamless as Cash App’s dedicated payment focus. If your primary need is a digital way to pay back friends, Cash App is the industry standard for a reason.
While Chime’s P2P service is functional, Cash App’s larger user base and payment-centric design make it the go-to choice for this task. It’s one of the best P2P payment apps available.
Investing: Can You Buy Stocks and Bitcoin on These Apps?
For users looking to do more than just save, investing capabilities are a key differentiator in the chime vs cash app analysis. Cash App provides simple, integrated tools for buying stocks and Bitcoin, a feature Chime does not currently offer.
With Cash App Investing, you can buy and sell stocks with as little as $1. It supports fractional shares, meaning you can invest in high-priced stocks like Amazon or Tesla without needing to buy a full share. This makes investing highly accessible for beginners.
Cash App was also one of the first major fintech apps to integrate Bitcoin. Users can easily buy, sell, and transfer Bitcoin directly within the app. This has made it a popular entry point for people curious about cryptocurrency.
Chime does not have a native investing platform. Its focus is strictly on banking products: checking and savings. To invest, a Chime user would need to connect their account to a separate brokerage app like Robinhood or Fidelity.
Therefore, if you want an all-in-one app for payments, spending, and basic investing, Cash App is the only choice between the two. Its simplicity is its greatest strength for new investors.
- Cash App: Offers integrated stock and Bitcoin investing.
- Chime: Does not offer any native investing features.
- Fractional Shares: Cash App allows investing with as little as $1.
- Accessibility: Cash App is a strong choice for beginner investors wanting a single app.
The Winner: Chime for Banking, Cash App for Payments & Investing
After a thorough comparison, the conclusion is straightforward. The better app depends entirely on your primary goal. There isn’t one app that’s best for everything.
Chime is the winner for anyone seeking a primary bank account replacement. Its combination of a no-fee checking account, a competitive savings APY, a huge fee-free ATM network, and the invaluable SpotMe overdraft feature makes it a powerful and complete banking solution.
It reliably covers all the core needs of daily banking, from receiving a paycheck with early direct deposit to paying bills and saving for the future. It’s a true alternative to a brick-and-mortar bank.
Cash App is the winner for peer-to-peer payments and simple, accessible investing. Its platform is unmatched for quickly sending money to friends. The integrated ability to buy fractional stocks and Bitcoin makes it an excellent entry point for new investors.
While it has banking features, they are less comprehensive than Chime’s. Cash App is best used as a powerful digital wallet and investing tool that complements a primary bank account, which could very well be Chime.
Frequently Asked Questions
Which is safer, Chime or Cash App?
Both Chime and Cash App are safe to use. They partner with FDIC-insured banks to protect your deposits up to $250,000. Both also use encryption and modern security features to protect your account information and transactions.
In the chime vs cash app debate, who has better overdraft protection?
Chime has far better overdraft protection. Its SpotMe feature offers eligible members fee-free overdrafts on debit card purchases, starting at $20 and potentially going up to $200. Cash App does not offer a comparable fee-free overdraft service.
Can I use Chime and Cash App together?
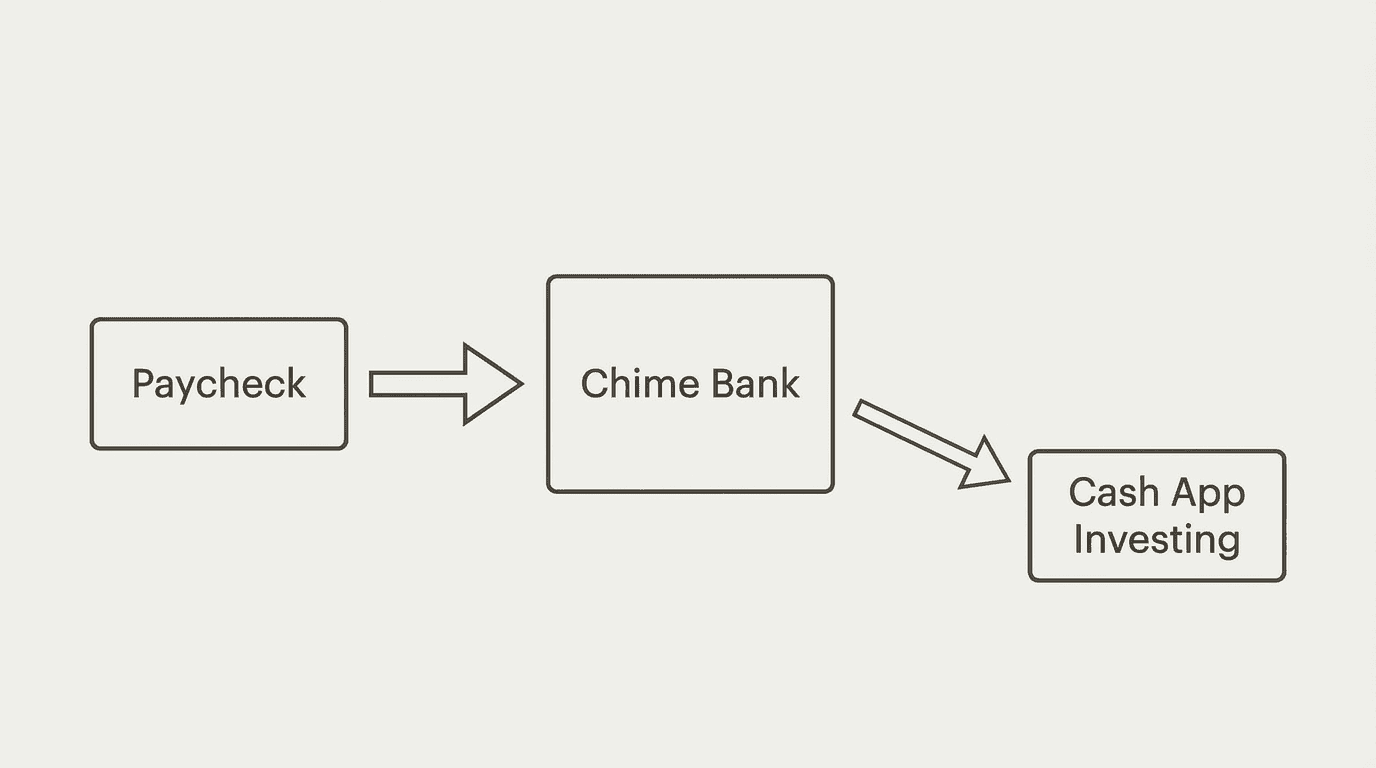
Yes, many people use both apps together. You can use Chime as your primary bank for direct deposits and savings, and link your Chime account to Cash App to easily send money to friends or use its investing features.
For chime vs cash app, which is better for getting paid early?
Both Chime and Cash App offer direct deposits up to two days early compared to many traditional banks. This feature is dependent on the payer’s payroll provider, so performance is generally comparable between the two. Neither has a distinct advantage here.
Does Chime or Cash App have better customer support?
Both platforms primarily rely on in-app chat and email for customer support, which can be a point of frustration for some users. Neither is known for standout phone support like a traditional bank. User experiences vary widely for both services.
Can you buy Bitcoin with Chime?
No, you cannot buy Bitcoin directly through the Chime app. Chime does not have a native cryptocurrency or stock investing platform. To buy Bitcoin, you would need to use an external service like Cash App or a dedicated crypto exchange.